

What is a good credit score in Canada in 2025? It’s a question more Canadians are asking as credit requirements tighten, and lenders use increasingly detailed scoring models to make decisions.
A good credit score can open doors to lower interest rates and more borrowing options, but hitting the right number isn’t always straightforward. Different lenders, credit bureaus, and scoring systems may each define “good” slightly differently.
That’s why understanding your credit score — how it’s calculated, what impacts it, and how it’s used — is essential today. Whether you’re applying for a loan, qualifying for a mortgage, or just trying to keep your credit report in great shape, knowing where your score stands can make a big difference.
This guide breaks down everything you need to know about credit score ranges in Canada, what’s considered a strong score in 2025, and how to improve yours over time.
What is a credit score range?
Credit scores in Canada range from 300 to 900. These numbers are calculated by credit reporting agencies based on your credit report, and they help lenders determine your risk level as a borrower.
The two main credit bureaus in Canada are Equifax and TransUnion, and each may provide slightly different scores due to differences in the data they collect or how frequently they update your file.
Here is a breakdown of the credit score ranges:
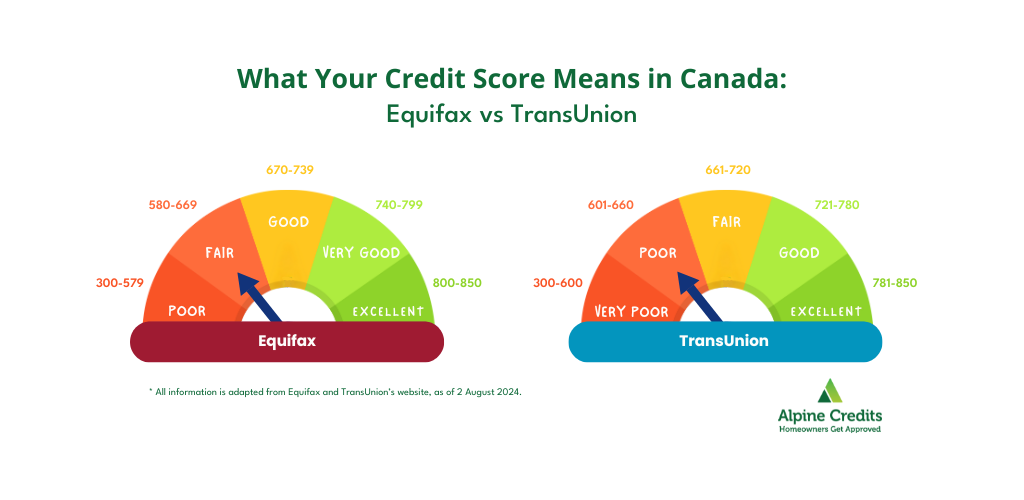
These ranges are based on credit scoring models used by the major credit bureaus. A higher score not only improves your chances of approval for new credit but can also affect the type of financial products available to you, such as premium credit cards, higher credit limits, and lower interest rates.
In essence, your credit score is a financial passport. Understanding the different ranges helps you evaluate your current financial standing and determine what actions you can take to improve your score over time.
What is a good credit score in Canada?
Depending on the credit rating agency, a score of around 660 or more may mean “fair” or “good” in Canada.
Most lenders will view you as a responsible borrower if you fall into the “Good” or “Very Good” categories. This means you’re more likely to be approved for loans and credit cards and often receive better interest rates and terms.
For instance, let’s say you’re applying for a car loan. A credit score of 700 or above could secure you a significantly lower interest rate than someone with a score of 600. Over the life of a loan, this could translate into thousands of dollars in savings.
Having a good credit score also allows you to:
- Qualify for higher credit limits
- Negotiate better loan terms
- Receive pre-approvals from lenders
- Experience faster processing during credit applications
Remember, however, that each lender may interpret your score differently. Some financial institutions or credit card issuers might prefer scores in the 700+ range to offer their most competitive products.
What impacts your credit score?
Several factors influence your credit score. These are evaluated by the credit bureaus using credit scoring models. Understanding these factors can help you maintain or improve your score.
Credit utilization
Credit utilization measures how much of your total available credit you’re currently using. It’s expressed as a percentage: if you have a total credit limit of $10,000 and you’re using $3,000, your utilization ratio is 30%.
Maintaining a credit utilization ratio below 30% is ideal. Higher ratios suggest to lenders that you might be overly reliant on credit, which could pose a risk. For example, if your credit card balance consistently hovers near the maximum limit, it may hurt your credit score, even if you make payments on time.
Using credit sparingly and paying down balances can positively influence your score. If you’re carrying a higher balance compared to your available credit, consider paying it down or requesting a credit limit increase (without increasing spending).
Payment history
Your payment history is the most critical factor in your credit score. This includes any late payments, missed payments, or accounts sent to collection agencies. Making consistent, on-time payments shows lenders you are dependable.
Even one skipped or late payment could remain on your report for up to six years. That’s why it’s important to automate payments or set reminders. Always aim to make at least the minimum payment by the due date on every credit account you have.
Credit history
The longer your credit history, the more data lenders have to assess your reliability. If you’ve managed credit responsibly over many years, that can lead to higher credit scores.
What’s credit history?
Your credit history refers to the length of time you’ve had credit accounts open, including:
- When your oldest account was opened
- The average age of all accounts
- Account activity over time
A long, stable credit history with few or no negative marks can increase your creditworthiness. Try not to close older credit accounts, as this may reduce your average account age and negatively impact your score.
Types of credit
Lenders like to see that you can manage a variety of credit responsibly. This is known as your credit mix. It includes:
- Revolving credit (e.g., credit cards)
- Installment loans (e.g., personal loans, mortgages)
- Retail credit cards or lines of credit from department stores
Having only one type of credit might limit your score. Diversifying your credit mix can help demonstrate financial maturity and the ability to handle various credit accounts.
How to check your credit score
In Canada, you can request a free copy of your credit report from both Equifax and TransUnion (procedures vary by bureau); many banks and credit card issuers also offer free, ongoing access to your credit score.
When checking your score, keep in mind that:
- You may see different credit scores depending on the scoring model used.
- Checking your own credit report does not affect your credit score (this is considered a soft inquiry).
It’s wise to check credit reports regularly to look for errors, signs of fraud, or incomplete account information. You can request corrections from the credit reporting agency if you notice any discrepancies.
What is a bad credit score in Canada?
A bad credit score in Canada could be anything under 600, but this again depends on the respective credit rating agency. This can significantly limit your access to financial products, as you may be denied credit or offered very high loan rates that can make borrowing expensive.
With a low score, you might also face:
- Lower credit limits
- High security deposits for utilities or rental agreements
- Difficulty securing housing or employment in certain industries
What lowers your credit score?
A bad score might result from a history of late payments or high credit utilization. Many other everyday financial actions can result in lower scores, including:
- Maxing out your credit card limit
- Defaulting on loans
- Applying for too many credit checks
- Relying too heavily on revolving debt
- Closing old accounts unnecessarily
- Ignoring errors in your credit report
However, it’s never too late to rebuild with smart, consistent financial habits. Being proactive with your financial activity and credit profile is key to preventing a drop in your score.
How to increase your credit score
If your credit score needs improvement, there are certain actionable steps you can take as per the Financial Consumer Agency of Canada (FCAC). Some of them are:
Don’t miss any payments
Your payment history matters the most. Always make at least your minimum payment on every credit account and never allow a bill to go unpaid. Consider setting up automatic payments to avoid late payments.
Limit credit checks
Too many credit checks within a short period can signal to lenders that you’re in financial trouble. Be selective about when and where you apply for new credit.
“Hard” vs “soft” inquiries
Not all credit checks are the same. A hard inquiry happens when a lender reviews your credit report as part of a credit application, which can affect your score. A soft inquiry occurs when you or a business checks your report for informational purposes — it’s visible only to you and doesn’t impact your score.
Diversify credit mix
Add different types of credit to your portfolio over time. For example, if you have a credit card, consider a small auto loan or secured line of credit to improve your credit mix. Just ensure you can manage all debts responsibly.
Use credit sparingly
Treat your available credit like a safety net, not a target. The less of it you regularly use, the more it shows lenders and credit bureaus that you manage your finances with discipline and aren’t dependent on borrowing to get by.
How is a credit score calculated?
Credit scoring models are complex, but many use similar key factors. Here’s how a credit rating agency may typically calculate your credit score:
- Payment history: 35%
- Credit utilization: 30%
- Length of credit history: 15%
- Types of credit: 10%
- New credit inquiries: 10%
Different lenders report to credit bureaus on different schedules, and each credit reporting agency may use its own scoring model. That’s why you might see different credit scores across platforms.
NOTE: The percentage weights shown here are based on a widely used credit scoring framework. Equifax and TransUnion each have their own proprietary models, so exact weightings may vary.
What is your credit score used for?
Your credit score reflects your financial habits and history. Lenders, landlords, and even some employers use it to assess your reliability and determine how you manage your financial obligations.
In most cases, your credit score is used to:
- Decide whether you qualify for financial products like a credit card, mortgage, or line of credit
- Set the interest rate you’ll pay when you borrow money, with higher credit scores typically receiving lower rates
- Evaluate your eligibility to rent a home or apartment
- Determine the need for a deposit with utility companies or mobile service providers
- Assess your financial responsibility in employment screenings
A strong credit score signals to potential lenders and service providers that you will likely repay what you borrow and manage bills responsibly. On the other hand, lower scores may suggest trouble paying past debts or inconsistent payment patterns, which can result in less favourable terms or even denials.
Alpine Credits: Focused on your equity, not your credit score
Your credit score matters, but it’s not the only thing that should. At Alpine Credits, we take a different approach from traditional lenders. We believe that your home equity should carry more weight than a three-digit number.
Whether you have a good credit score, a fair one, or you’re recovering from a few missed payments, you may still qualify for a home equity loan. If you own at least 25% of your home, your credit score doesn’t need to stand in your way.
Here’s how we make borrowing simple:
- Apply online – Submit your application online—no credit score or income history required. Our process is fast, easy, and secure.
- Get approved quickly – If you own a home with sufficient equity, you may be eligible for a home equity loan. Many of our clients receive approval within 24 hours.
- Access your funds fast – After approval, your loan is funded directly into your account, often within days.
You can use your home equity to consolidate debt, cover unexpected expenses, fund home improvements, or take advantage of a new financial opportunity without being held back by traditional credit requirements.
Get a free, no-obligation quote today from one of our Financial Solutions Specialists and see how your equity can work for you, even if your credit score needs work.