



While traditional banks use credit scores and financial statements to determine loan eligibility, alternative lenders and private lenders can provide substantial funding even if your credit score is low. Read on to learn more about the financing options for those with less-than-perfect credit in British Columbia.
Key Takeaways:
- Bad credit loans are legal and available in British Columbia.
- Options range from home equity loans for homeowners to equipment loans and working capital solutions for small business owners.
- BC homeowners and small businesses with available equity or assets may qualify with Alpine Credits regardless of credit score.
What are bad credit loans in British Columbia (BC)?
A loan for bad credit in BC is a financing option designed for borrowers with bruised credit. Traditional banks typically require a minimum credit score of 600 and rely heavily on credit scores and payment history to assess creditworthiness. In contrast, bad credit lenders evaluate eligibility based on collateral or asset value, offering more flexible options for those with lower credit scores.
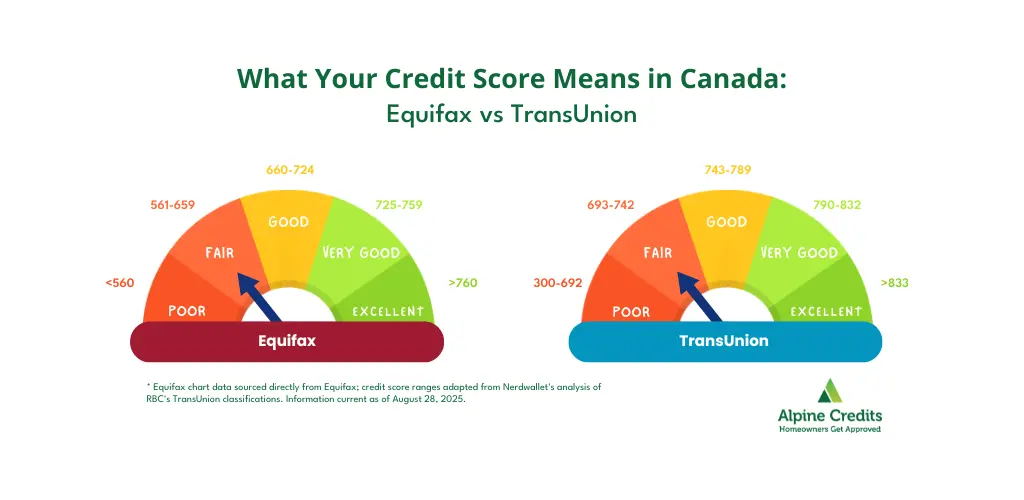
If your credit score falls below 600, securing a traditional bank loan becomes significantly harder, often resulting in lower approved loan amounts and higher interest rates.
Alternative lenders offer flexible financing options tailored to low credit scores. Whether labelled as online loans, private lender loans, or no-credit-check loans, their core purpose remains the same: providing bad-credit borrowers with fast funding and access to more money when traditional banks say no.
Can you get a bad credit loan in BC?
Yes, you can secure bad credit financing in BC through alternative lending options. Whether you need a personal loan, equipment financing, or a home equity loan, alternative lenders evaluate overall value and income stability rather than relying solely on your credit history.
What type of bad credit loans are available in BC?
There are different ways to obtain bad credit loans in Vancouver and across BC. They usually fall into two major categories: unsecured and secured.
Unsecured personal loans
Unsecured loans are loans where approval is usually based on your creditworthiness because the lender doesn’t require an asset as collateral. Unsecured loans do not require collateral but may have stricter approval criteria, while bad credit loans from alternative lenders often carry higher interest rates than those from traditional banks.
Getting approved for unsecured loans can require that you have a strong credit score or a stable source of income. Some lenders may offer options for those with lower credit scores, but the terms may include a high interest rate. Loan terms for bad credit loans commonly run from 6 months to 5 years.
Secured personal loans
A secured loan requires you to provide an asset as collateral. The role of collateral is to guarantee to the lender that you will repay your loan. As a result, approval criteria are far more flexible, rates are lower, and you benefit from flexible terms.
- Car title loans: Provide your vehicle as collateral to secure fast funding. While processed quickly, rates can be high.
- Equipment loans and equipment financing: For business owners who need to finance equipment, buy used equipment, or purchase heavy machinery such as dump trucks from a private seller, equipment lenders offer specialized loans. This helps smooth out your cash flow cycle without interrupting daily business and core operations.
- Home equity loans: Your home is a valuable asset. You can find out your available equity by subtracting your outstanding mortgage balance from the appraised market value of your property.

Which loan is most accessible with bruised credit in BC?
For homeowners, a home equity loan is the most accessible option in BC. Because the loan is backed by property value rather than credit history, approval rates may be significantly higher compared to unsecured options. For business owners, securing funding through an equipment purchase or asset-backed loan offers a similar path to high approval rates.
Where to get loans for bad credit in BC
While major banks have strict guidelines, you can secure financing solutions from credit unions or alternative private lenders. It is advisable to check if lenders are registered and licensed in British Columbia before borrowing.
Credit unions
A credit union is a financial institution owned by its members and operated as a non-profit. Credit unions may offer more flexible lending options than major banks, since decisions are made by the board of directors, and all members can dictate how the credit union operates.
You may be able to get a loan from your credit union if you are in one, since they focus more on serving their members. They may allow those with lower credit scores to get a loan, but the process can take just as long as it would at the bank.
Alternative lenders
Alternative lenders are institutions that have more flexible loan approval criteria than traditional banks and credit unions. Regardless of your credit score or income, some alternative lenders allow you to borrow a significant amount.
One example of an alternative lender is Alpine Credits, which focuses on home equity loans. Regardless of your credit score, you may qualify as long as you have 25% equity or more in your property.
Bad credit loans for BC homeowners: What Alpine Credits offers
Approval on equity, not credit score
Alpine Credits focuses on the equity in your home rather than your credit score or income. If you own at least 25% equity, you may qualify. This allows Alpine Credits to support BC homeowners facing job loss, divorce, medical issues, or other credit challenges.
For full details on how home equity loans work, see Alpine Credits’ home equity loan guide.
Ways you can use a secured bad credit loan in BC
- Consolidate multiple debts: Streamline high-interest debts into one manageable monthly payment.
- Home renovation: Reinvest in your home to increase its overall market value.
- Business investments: Inject capital into your business to buy inventory, manage operational expenses, or handle a down payment for commercial expansion.
Who is eligible for a bad credit loan in BC?
While eligibility often requires proof of income and residency, Canadian homeowners in British Columbia with at least 25% home equity are eligible for a loan with Alpine Credits, regardless of credit history or income verification.
Benefits of bad credit loans in BC
A bad-credit loan can offer many benefits. The following are some of the advantages and reasons people choose to take out bad credit loans in British Columbia.
- Flexible approval criteria: Eligibility is based on collateral value, not strict credit scores.
- Quick processing: Get fast approvals and funds in your account within a few days.
- Multipurpose funding: Use the capital for debt consolidation, home improvements, or business growth.
Get a bad credit loan in BC with Alpine Credits
Getting financial assistance shouldn’t be limited by your credit rating. With a home equity loan from Alpine Credits, you can access the funding you need with flexible eligibility requirements and competitive terms.
If you’re a homeowner in BC with some home equity, you can easily apply for a loan that can be completed online in minutes:
- Apply online—the application with Alpine Credits is simple and can be completed in minutes.
- Get approved—as long as you own your home, you can get approved in as little as 24 hours. Alpine Credits, a direct lender, processes loan applications faster than many lenders in BC, allowing you to access funding significantly sooner.
- Receive funding—Alpine Credits will directly deposit the money in your bank account within a few days of your approval.
To find out more about home equity loans and what they can be applied to, contact a Financial Solutions Specialist at Alpine Credits to get a free, no-obligation quote today.
FAQ
Is it possible to pay off a bad credit loan early in BC?
Yes, some lenders offer bad credit loans with flexible repayment schedules, including the option for early repayment. Terms vary depending on the specific loan agreement and lender policies.
How long are the averages for bad credit loans in BC?
Loan terms vary based on whether the loan is secured or unsecured, typically ranging anywhere from 6 months to 5 years.
Can I get a bad credit personal loan in Vancouver?
Yes, bad credit personal loans, home equity loans, and business loans are widely available to residents across Vancouver and the Lower Mainland.
How do I qualify for a bad credit loan in BC?
Qualification depends on the lender. While some lenders may require proof of minimum income or an upfront down payment, securing a home equity loan with Alpine Credits is straightforward since they prioritize your home equity over traditional checks on your credit report and income.