


Private lenders in Ontario are transforming the borrowing landscape for many in 2026, offering unique financing opportunities that traditional banks may overlook for borrowers. So, whether you’re a homeowner looking to renovate or consolidate multiple bills in Ontario, understanding private mortgages and lenders can help you navigate your financial options more effectively.
Here’s what you need to know about private lenders in Ontario and how Alpine Credits can provide you with flexible financing options quickly.
Who are the private mortgage lenders in Ontario?
Private mortgage lenders in Ontario are typically individuals or financial institutions that provide secured loans. They can be real estate investors looking to earn returns on their capital or private companies specializing in secured financing.
Unlike traditional mortgage lenders, such as banks or credit unions, private mortgage lenders have more flexible approval process that is equity based, focusing on the property’s value and collateral rather than strict income verification or credit history.
They can include:
- Lower credit scores: Private lenders may be more lenient regarding credit scores, allowing borrowers with less-than-perfect credit histories to qualify for private loans.
- Collateral: Loans are often secured by the property itself, which provides a safety net for lenders and allows them to approve borrowers who may not meet traditional lending criteria.
- Home equity: Borrowers build equity over time as they pay their mortgages. Some alternative lenders primarily focus on home equity rather than income or credit scores. Borrowers then use this equity to access additional funding through home equity loans.
View this post on Instagram
Who are the best private mortgage lenders in Ontario?
Choosing the right private lender involves comparing private mortgage rates, fees, and lending niches. Here are some of the most reputable private lenders in 2026, known for their specialized products:
- Alpine Credits: Specializes in home equity loans and offers the most accessible equity-based lending in Ontario. Alpine Credits provides approvals in under 24 hours without requiring income verification or credit checks, making them the premier choice for urgent debt consolidation, home renovations, or business capital.
- Magenta MIC: Known for a strong focus on Eastern Ontario and residential urban markets, Magenta Mortgage Investment Corporation offers equity-based lending for borrowers who do not meet traditional bank criteria.
- DV Capital Corp: A Toronto-based boutique mortgage firm that offers a wide spectrum of mortgage solutions, including traditional mortgages, alternative financing, and private mortgages for borrowers with diverse credit profiles.
- Cannect Home Financing: Operates as both a mortgage broker and direct lender, offering private mortgage options and second mortgages with a digital application.
- Tembo Financial: Focusing on 48-hour approval process and residential advances, primarily assisting homeowners with bridge financing and urgent financing needs.
Most private lenders in Ontario offer a range of loan products, including personal installment loans, auto loans, debt consolidation loans, and business loans. These loans usually have higher interest rates than banks, but can be a valuable alternative for borrowers who do not qualify for traditional financing.
How do private mortgages work in Ontario?
Private mortgages function similarly to traditional mortgages but with key differences.
First, the application process for private mortgages can be much faster, often with less paperwork than traditional bank loans. Private lenders focus more on your home equity rather than your credit score or income.
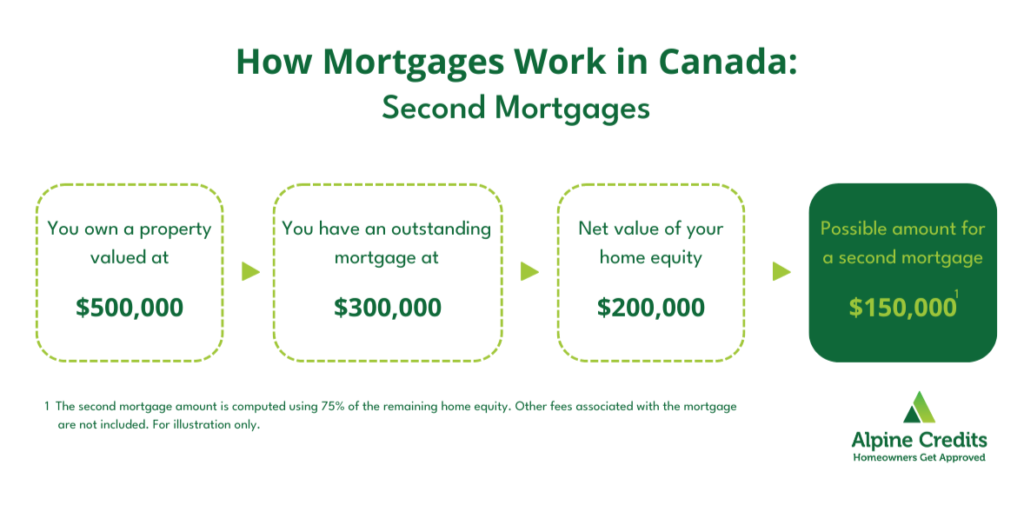
Since the loan amount depends primarily on the value of your home equity, private mortgages can be used for any purpose, although common applications include debt consolidation, home renovation, and capital for business.
Lastly, private lenders offer flexible terms like interest-only payments adjustable schedules. Private mortgages typically have shorter repayment periods, lasting 1 to 3 years, and function as a short-term bridge that requires a solid exit strategy for future refinancing.
Regulations for private lenders in Ontario
In Ontario, private lending and brokering are governed by the Financial Services Regulatory Authority of Ontario (FSRA). To prevent predatory lenders and ensure market stability in the non-traditional mortgage sector, FSRA enforces the following:
- MBLAA Compliance: Lenders and brokers must adhere to the Mortgage Brokerages, Lenders and Administrators Act, requiring all individuals and businesses in Ontario who carry out regulated mortgage brokering activities be licensed with FSRA.
- Full Disclosure: FSRA’s Supervision Plan (2025-2026) mandates that all lender fees, origination fees, and brokerage commissions be explicitly disclosed in the Cost of Borrowing statement. Ontario law also requires lenders to clearly disclose penalties for missed payments to ensure transparency and prevent disputes.
- Criminal Interest Rate: As of 2025, federal law reduced the maximum interest rate from a 60% effective annual rate (EAR) to a 35% Annual Percentage Rate (APR) for most private consumer mortgages in Ontario.
Benefits of working with private lenders in Ontario
Working with private mortgage lenders means choosing an alternative financing option. Private lenders offer several advantages over traditional lenders:
| Feature | Private Lenders | Traditional Lenders |
| Approval Speed | 24 – 48 Hours | 24 Hours to several days |
| Primary Criteria | Home Equity (LTV) | Income & Credit Score |
| Paperwork | Minimal | Extensive |
Note. The data for Private lenders are from Alpine Credits (2026). The data for Traditional Lenders are as follows: Approval Speed data is from Remax (2025) ; Primary Criteria data is from Financial Consumer Agency of Canada (2025); Paperwork data is from Canadian Mortgage and Housing Corporation (2026).
Private mortgage lenders often have faster approval processes than banks, which is particularly helpful in situations when timing is crucial, such as when consolidating debts or when emergency funding is needed.
Private mortgage lenders are also more accommodating for borrowers with poor credit, high debt, or credit challenges, and may consider non-traditional income sources such as self-employment or other unconventional income.
How to find a private lender in Ontario? 5 things to consider
According to Canada Mortgage and Housing Corp. (CMHC), alternative lenders account for more than 20% of the country’s mortgage market—which has been rising since 2023. To help you make the best choice when it comes to borrowing funds from non-traditional sources, here are five things to consider when choosing a private lender in Ontario:
1. Interest rates and fees
Private mortgage lenders typically charge higher interest rates than traditional banks for mortgage loans. In 2026, the average interest rate in Ontario can go well over 10%, compared to traditional lenders’ 6%. Always compare rates and understand the total cost of borrowing, including any hidden fees to ensure you’re getting a fair deal.
2. Reputation and credibility
The Mortgage Brokerages, Lenders, and Administrators Act, an overhaul of the 1990 Mortgage Brokers Act, governs private lending in Ontario and includes the licensing and regulatory regime requirements for mortgage lenders.
You can verify a private lender in Ontario through the following:
- Better Business Bureau (BBB): Visit the BBB website to assess the lender’s reputation and see any reported complaints or issues from previous clients.
- FRSA License Search: Verify the private lender’s legitimacy using the FRSA license search tool.
- Online Reviews: Read online reviews and testimonials to gauge their customers’ experiences.
Similar to a traditional mortgage lender, a reputable private mortgage lender should be transparent about their practices and willing to answer your questions.
3. Loan terms and flexibility
Private mortgages can be used for any financial goal. For example, home equity loans typically give out a lump-sum amount that can be used to consolidate high-interest debt and simplify mortgage payments, renovate a home, or fund a business idea.
Since private mortgages are often used as a short-term solution, it’s important for borrowers to be proactive in planning how they will handle their monthly payments and have a solid exit strategy in place.
4. Customer support
Good customer support can make a significant difference in your borrowing experience.
A CMHC survey found that 47% of borrowers are more likely to use a lender due to good service and support. In this case, lenders prioritizing personalized assistance and robust support systems will likely provide a satisfying borrowing experience.
5. Accessibility and approval
Consider how accessible the lender is. Some private lenders may have more stringent approval processes than others.
At Alpine Credits, all you need to qualify is to own your home, rather than solely on your income or credit history. This means that the greater the equity, the higher the funding potential. In addition, we make the process as quick and easy as possible. 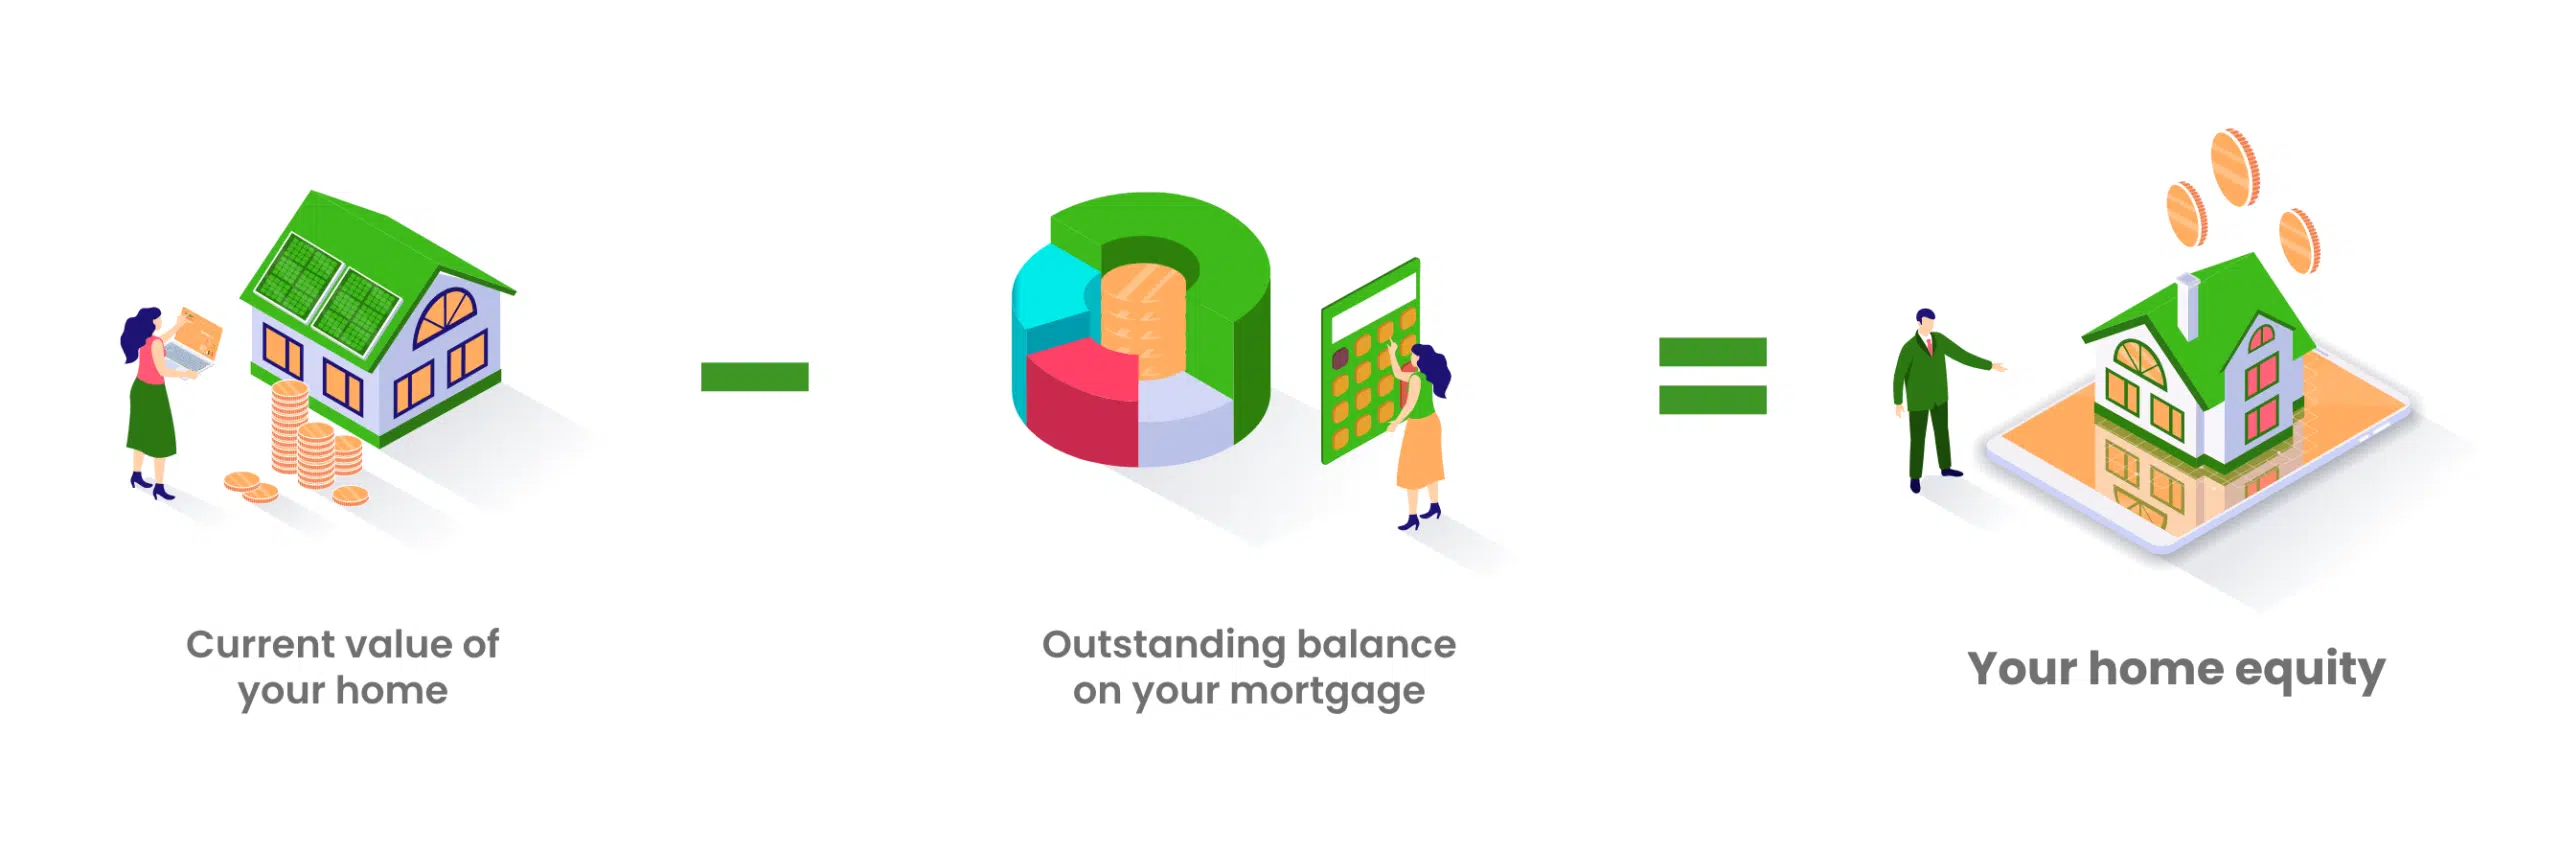
Access fast and flexible financing in Ontario with Alpine Credits
Alpine Credits simplifies the borrowing process by focusing on the equity you have built in your home. Since 1969, we have helped Ontarians bypass bank hurdles with a three-step process:
- Apply online— the application with Alpine Credits is simple, allowing you to finish it within minutes.
- Get approved— if you own at least 25% of your home, you are eligible for a home equity loan from Alpine Credits. Get approved as quickly as 24 hours.
- Receive funding— Alpine Credits will directly deposit the money in your bank account within a few days of your approval.
Contact one of our Financial Solutions Specialists for a free, no-obligation quote today.
Frequently Asked Questions (FAQs)
How much do private lenders charge in Ontario?
Private lenders in Ontario typically have higher interest rates than traditional banks, often ranging from 10% and up. This depends on the borrower’s circumstances, the loan-to-value (LTV) ratio, and the loan’s general risk level. Additionally, fees may apply, so it’s essential to review the total cost of borrowing.
Is private lending legal in Ontario?
Private lending is legal in Ontario. However, lenders must comply with provincial regulations. Borrowers should ensure they are working with licensed and reputable lenders to avoid potential pitfalls.
Is it easier to get a mortgage from a private lender?
For many borrowers, obtaining a private mortgage loan from a private lender can be easier than a traditional loan from a bank. Private lenders in Canada focus on factors beyond credit scores, such as property value and equity, allowing those with a poor credit history and non-traditional income to still qualify for funding.